
Berkshire's $900 Million Stake Validates a Controversial Software Play
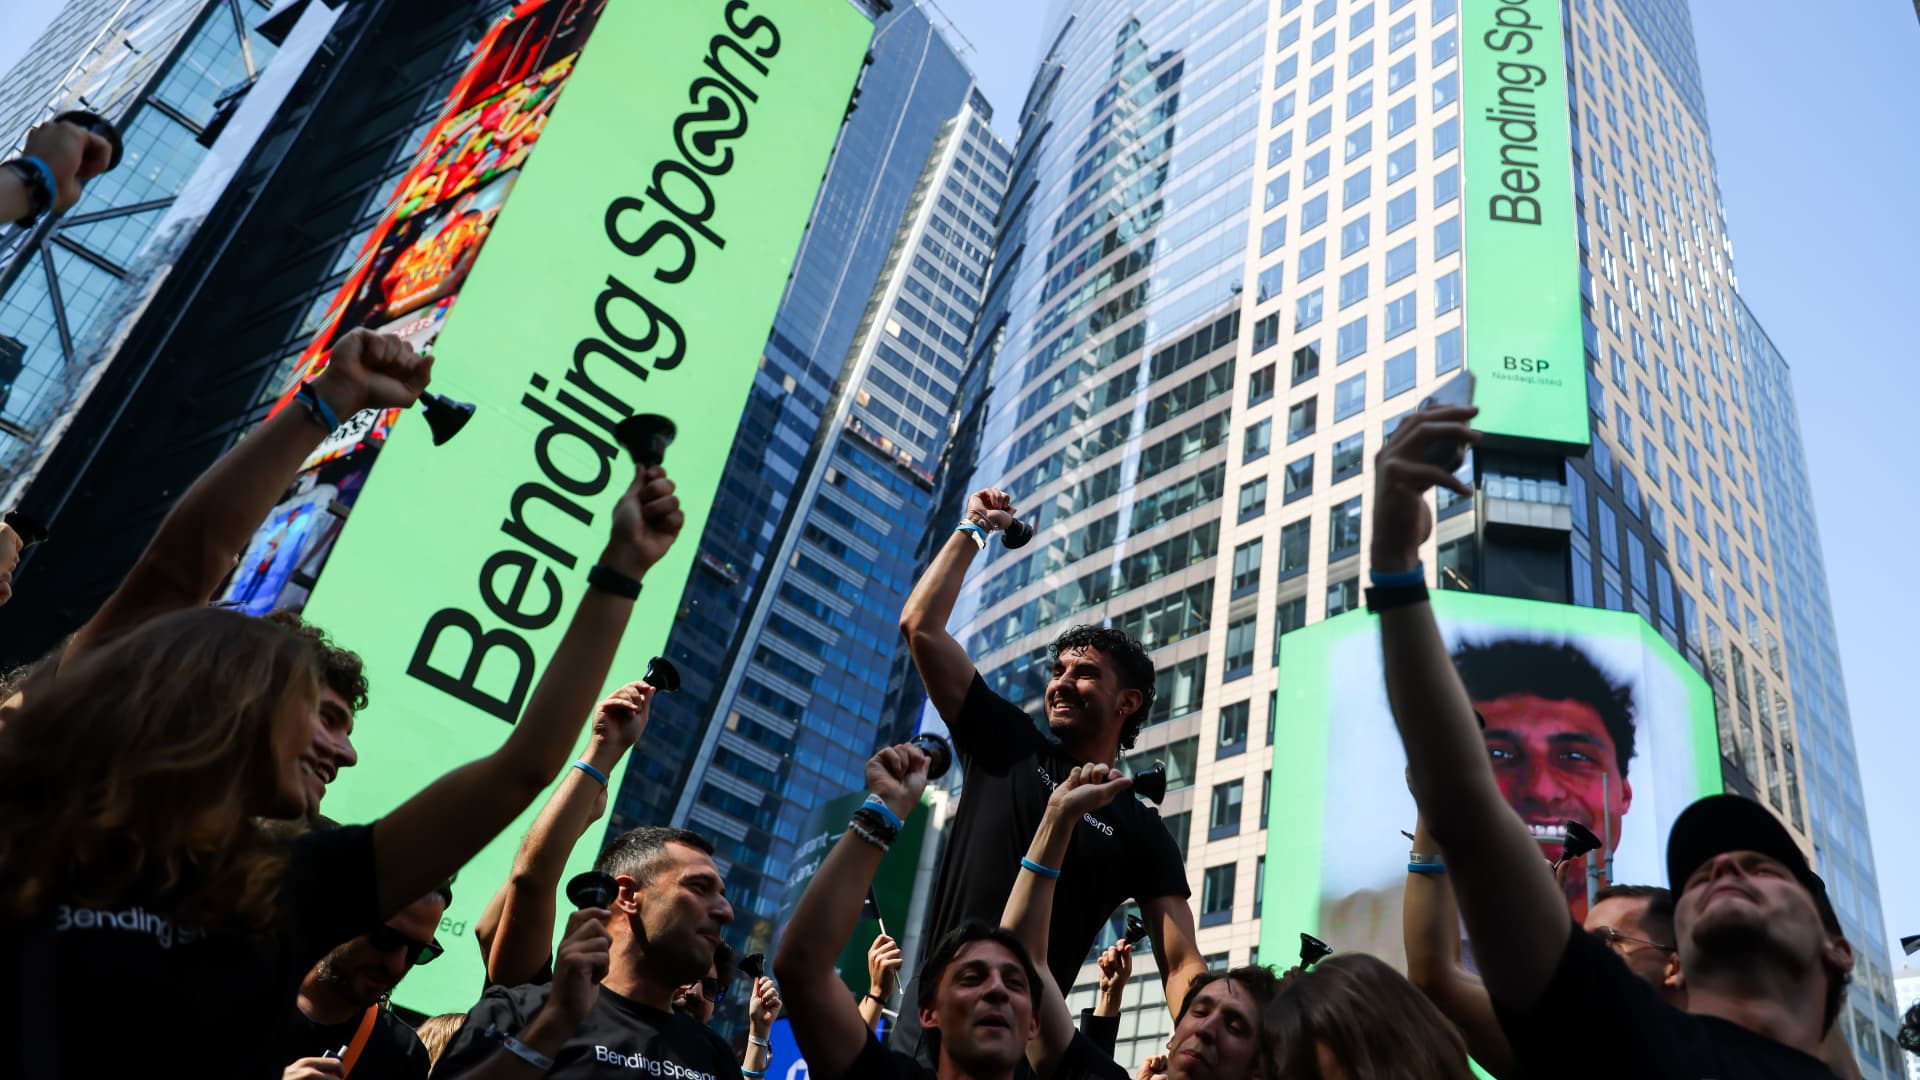
When Bending Spoons debuted on Nasdaq in late June, it was largely an unknown Italian holding company on the radar, bundling together aging internet brands such as AOL, Vimeo, Eventbrite, and Evernote. Fewer than four months after listing, the Milan-based firm has redefined itself as a destination for once-glorious software startups left behind by the artificial intelligence wave. That repositioning received its strongest endorsement this week from Berkshire Hathaway, the most storied holding company in global markets.
Benging Spoons, which characterizes Berkshire as a "longstanding inspiration" for its acquisition strategy, has accumulated more than $900 million in investment from the Omaha-based conglomerate, including a $330 million position revealed on Wednesday. The announcement sent the stock surging 41 percent in a single session, though a portion of those gains faded in the days that followed. The company finished the week with a market capitalization of roughly $30 billion, with shares closing at $47.07 on Friday.
Mizuho analysts framed the move as a significant endorsement, noting in a post-announcement report that Berkshire's decision to increase its stake just months after the IPO "provides another vote of confidence in the Bending Spoons model from one of the world's most respected long-term investors."
Job Cuts and Deep-Value Acquisitions Define the Flip Side
The same week that brought Berkshire's blessing also highlighted the cost of the consolidation strategy. In August, Bending Spoons announced its purchase of workflow software maker Airtable for approximately $1.3 billion, a price nearly 90 percent below the valuation Airtable commanded at its late-2021 peak. On Monday, the company confirmed that a "large portion of the pre-acquisition team" at Airtable would be departing with "substantial separation packages."
Those workforce reductions are not isolated incidents. Similar layoffs were previously carried out at Evernote, Vimeo, WeTransfer, and other portfolio companies. For the broader technology sector, the pattern illustrates how rapidly fortunes can shift in the AI era, as large-language-model agents increasingly replace the work of software developers and the products they created. With Anthropic and OpenAI both advancing toward trillion-dollar valuations, enterprises are redirecting budget toward these AI platforms, squeezing a long list of traditional SaaS names. The phenomenon has been dubbed the "SaaSpocalypse."
The impact is visible in public markets: shares of Intuit, HubSpot, and Adobe have each fallen at least 30 percent year to date. Meanwhile, a wave of once-celebrated private SaaS companies struggle to raise capital, and the public market shows little appetite for new IPOs. Last month, Bending Spoons agreed to acquire collaboration software vendor Miro, which had once carried a $17.5 billion valuation, for just $1.36 billion.
Ethan Kurzweil, founder and managing partner at Chemistry VC, captured the binary reality facing software firms: "You're either like a hot thing or you're nothing." Kurzweil, who personally uses Airtable, acknowledged that many solid SaaS products with strong teams remain on the market, but stressed that "they're not on the frontier anymore."
A Different Playbook from Traditional Private Equity
Bending Spoons was founded in 2013 by friends Luca Ferrari (now CEO), Matteo Danieli, and Francesco Patarnello. According to the IPO prospectus, a mobile app they had built called Evertale failed to gain traction, and the trio used the roughly $40,000 they had left to create an operating company rather than continue building "products nobody wanted."
The company's major acquisitions have accelerated in recent years: Evernote in 2022, Brightcove in 2024, and then Vimeo, AOL, and Eventbrite all in 2025. The IPO on June 30 raised approximately $1.7 billion at $29 per share, with shares hitting the Nasdaq the following day.
In prior decades, the dominant acquirers in the enterprise software space were private equity giants Thoma Bravo and Vista Equity Partners, whose strategy centered on buying undervalued SaaS companies, driving costs down, and eventually selling or taking the assets public at a premium. Bending Spoons deliberately departs from that model. Rather than targeting exits, the company aims to generate sustained operating profits from its portfolio, echoing the Warren Buffett approach. The key distinction is that Bending Spoons concentrates exclusively on technology and takes a hands-on role in software development, operations, and staffing decisions.
Nick Mehta, former CEO of Gainsight, which was sold to Vista in 2020, suggested that traditional PE firms are now constrained: "They paid much higher prices and have so many troubled companies that it's difficult for them to take swings now." Mehta noted that the term "Bending Spooned" has become a verb in Silicon Valley, shorthand for companies being scooped up at a fraction of their former value. "Unfortunately, a lot of my friends in that game are stuck. Investors want out but there are no buyers. Anything pre-ChatGPT is legacy now," he said. Thoma Bravo and Vista did not respond to interview requests. Bending Spoons told CNBC it has not been outbid for a target in "several years."
Lloyd Walmsley, an analyst at Mizuho, emphasized that the company's operating depth sets it apart. "I think there aren't a lot of people that do what these guys do in terms of the depth of operations and the willingness to make substantial product changes," Walmsley said. "It's not typical of traditional private equity firms to make anywhere near this level of change."
Revenue Growth and the Question of Sustainability
For customers of acquired brands, the consolidation strategy has sometimes meant steeper prices. In April 2023, months after the Evernote deal closed, Bending Spoons raised the annual personal subscription from $70 to $130. Subsequent restructuring introduced a $100 "starter plan" and a $250 "Evernote Advanced" tier, replacing the prior $170 pro plan. Walmsley admitted his first reaction was to consider switching to Microsoft's OneNote but ultimately stayed, noting that the company is "really savvy at finding these things that they provide a lot of value, and the switching costs are really high. The price isn't that high relative to the switching cost."
CEO Luca Ferrari told CNBC that the "overwhelming majority" of the company's growth comes from executing additional acquisitions. "There are certain opportunities for improvement we can unlock over the first few years, and then the business will have whatever organic growth is intrinsic in that market," he said.
The financial picture as of the first earnings report as a public company, released in August, showed revenue more than doubling year over year to over $700 million, with growth driven almost entirely by acquisitions. Net income climbed 171 percent to $177 million. Notably, those figures predate the closing of the Airtable deal and the announcement of the Miro acquisition.
During that earnings call, an analyst asked whether Airtable signaled a long-term strategic pivot toward enterprise software. Ferrari responded that roughly half of Bending Spoons' revenue already comes from professional and business customers, largely through Brightcove and Vimeo's enterprise components. He clarified that the recent focus on software acquisitions is more about identifying value after a significant sector selloff. "Most enterprise SaaS businesses were valued at irrationally high levels until somewhat recently," Ferrari said. "We never saw those prices making any sense."
For Berkshire and other investors holding Bending Spoons stock, the thesis remains untested in the full sense. The acquired products must retain enough customer stickiness to justify rising prices in a market where AI is compressing margins across the software sector. In the quarters and years ahead, Wall Street will receive a definitive answer on whether this consolidation model can genuinely revive a class of software businesses that many once considered obsolete.