
A Prolonged Selloff Meets Brief Friday Relief
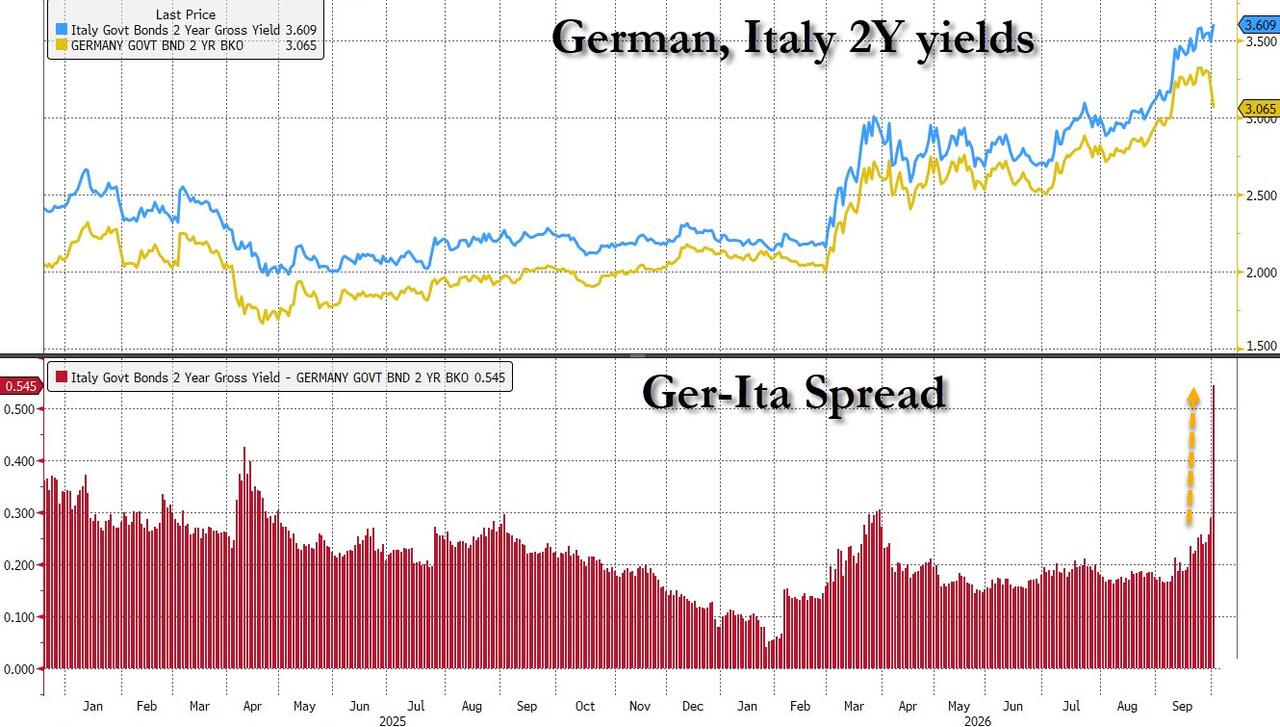
For several weeks now, the broader financial establishment has been grappling with a sustained bond selloff that has pushed yields up to the neighborhood of five percent. Rather than a single-day shock, the move has been a grinding, months-long process that has forced portfolio managers, hedgers, and institutional desks to recalibrate their assumptions about the risk-free rate.
Friday's session offered a moment of apparent calm, as yields eased and some of the worst selling paused. However, market participants quickly read the relief as short-lived. The temporary pause did not alter the underlying trajectory, and the consensus view is that the episode of elevated yields is far from over.
Cracks Widen Across Strategy Categories
The more concerning signal from the latest stretch of trading is that the damage from stubbornly high yields is no longer confined to a single asset class or strategy. Fixed-income managers, equity allocators, and alternative-asset investors are all reporting pressure as financing costs rise and discount rates shift. In other words, the cracks that were once localized in Treasury and credit markets are now appearing across investment strategies of every type.
This broadening of stress matters because it suggests that the adjustment to a higher-yield regime is still underway. Positions that were built around lower-rate assumptions are being unwound or restructured, and the ripple effects are reaching corners of the market that had previously been insulated.
What the Environment Means for Forex Participants
For currency traders, a persistent five-percent yield environment has direct implications. Higher domestic rates tend to support the local currency through carry-trade flows and capital inflows, but they also raise the cost of funding for leveraged positions. The growing cracks in broader risk assets can trigger de-risking episodes that pull liquidity out of exotic and mid-tier FX pairs, widening spreads and increasing slippage.
The key takeaway for forex desks is that the bond market's unresolved tension with the five-percent level is not a side issue. It is a structural input into currency valuation, volatility regimes, and the cost of hedging cross-border exposure. Until the yield trajectory stabilises, the forex market will continue to price in elevated uncertainty, and strategy adjustments that worked in a low-rate world may no longer hold.
In short, the brief Friday reprieve should not be mistaken for a turning point. The market is still in the process of absorbing a higher-yield reality, and the stress it generates is spreading well beyond the bond pit into every corner of the trading landscape.