
Asian Equities Hold Steadier Ground
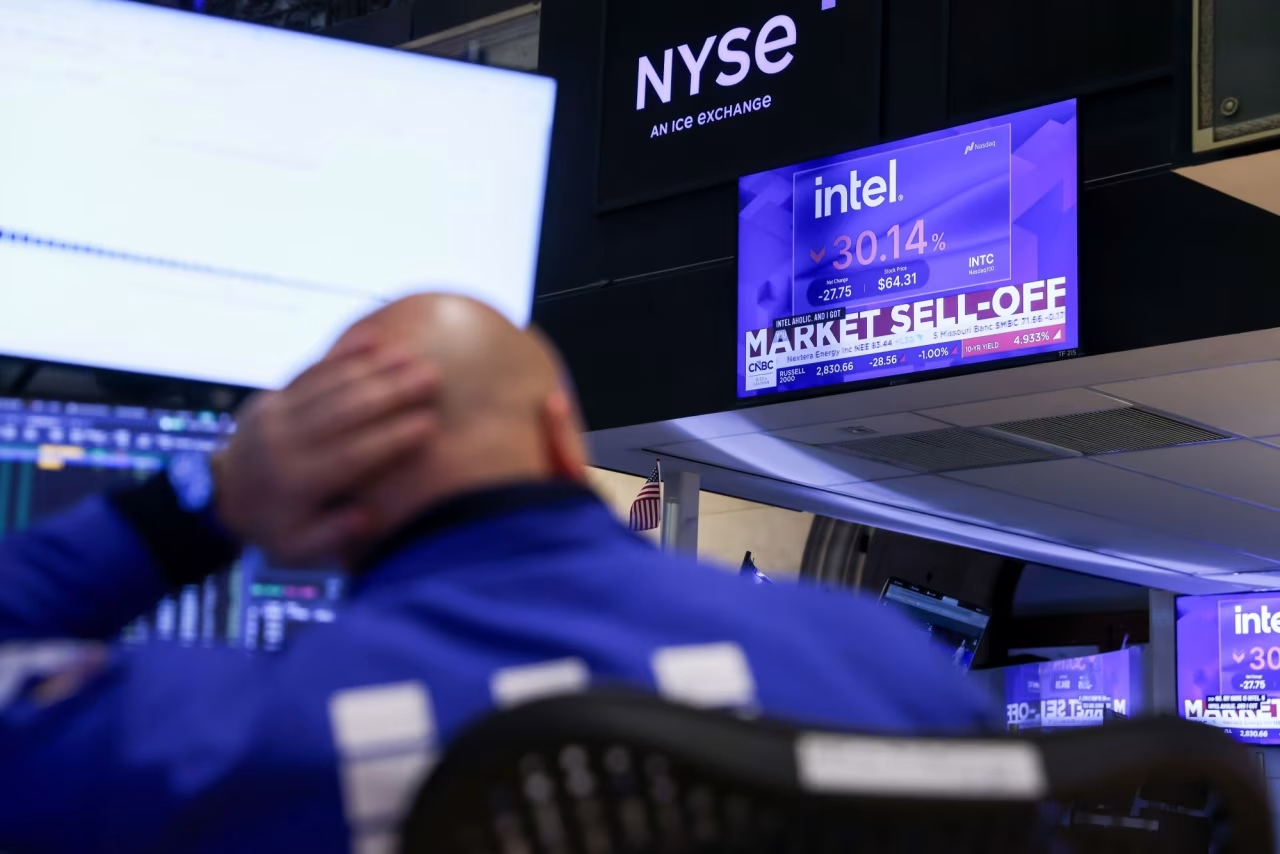
The wave of selling that had hammered technology-heavy indices during the prior trading session showed visible signs of exhaustion as Monday's early Asian trade unfolded. While regional equity benchmarks still closed the gap in negative territory, the magnitude of their decline was noticeably narrower than what Wall Street had endured just hours earlier. In practical terms, Asian-listed tech and growth names bled less than their American counterparts, suggesting that some of the panic-driven de-risking had already done its work before the Tokyo, Shanghai, and Seoul opens.
For portfolio managers and active traders watching cross-border flows, the relative resilience of Asian markets is a modest but meaningful signal. It implies that the sell-off was not a uniform global repricing of growth assets but was more heavily concentrated in US-listed technology and semiconductor names. The divergence also hints that regional liquidity buffers and differing exposure profiles are providing a partial cushion, even as the underlying sentiment shift persists.
US Futures Point Toward a Stabilizing Open
Futures contracts on major US equity indices turned positive in the pre-market window, a small but telling reversal from the heavy losses recorded in the previous close. The improvement in futures pricing suggests that some of the one-way risk had been flushed out of the market, and that buyers were at least probing for entry points at the lower levels. Traders should note that a futures uptick does not guarantee a full V-shaped recovery; it merely indicates that the most acute selling pressure had abated heading into the cash session.
From a risk-management standpoint, the easing in tech-sector selling reduces the likelihood of a cascading margin-call spiral across leveraged growth positions. That said, the underlying drivers of the initial selloff remain in play, and any fresh macro data or policy headlines could quickly re-ignite volatility.
Oil Continues Its Downward Drift
Crude oil prices slipped further in Monday's early trade, extending the commodity's broader weakness. The decline in the energy complex typically reflects a combination of softer demand expectations tied to the equity-market caution and a continued absence of supply-side shocks. For investors with exposure to energy equities, the sustained pressure on oil prices adds another layer of headwind to an already risk-off backdrop.
Taken together, the early Monday tape paints a picture of a market in a brief recovery pause rather than a confirmed trend reversal. Tech stocks have stopped free-falling, Asian equities are holding up marginally better, and US futures are edging higher, but the absence of a clear positive catalyst means the next session will still be heavily data-dependent. Traders in the stock space should remain cautious, keep position sizes disciplined, and watch for any further confirmation that the worst of the tech-driven volatility has passed.